
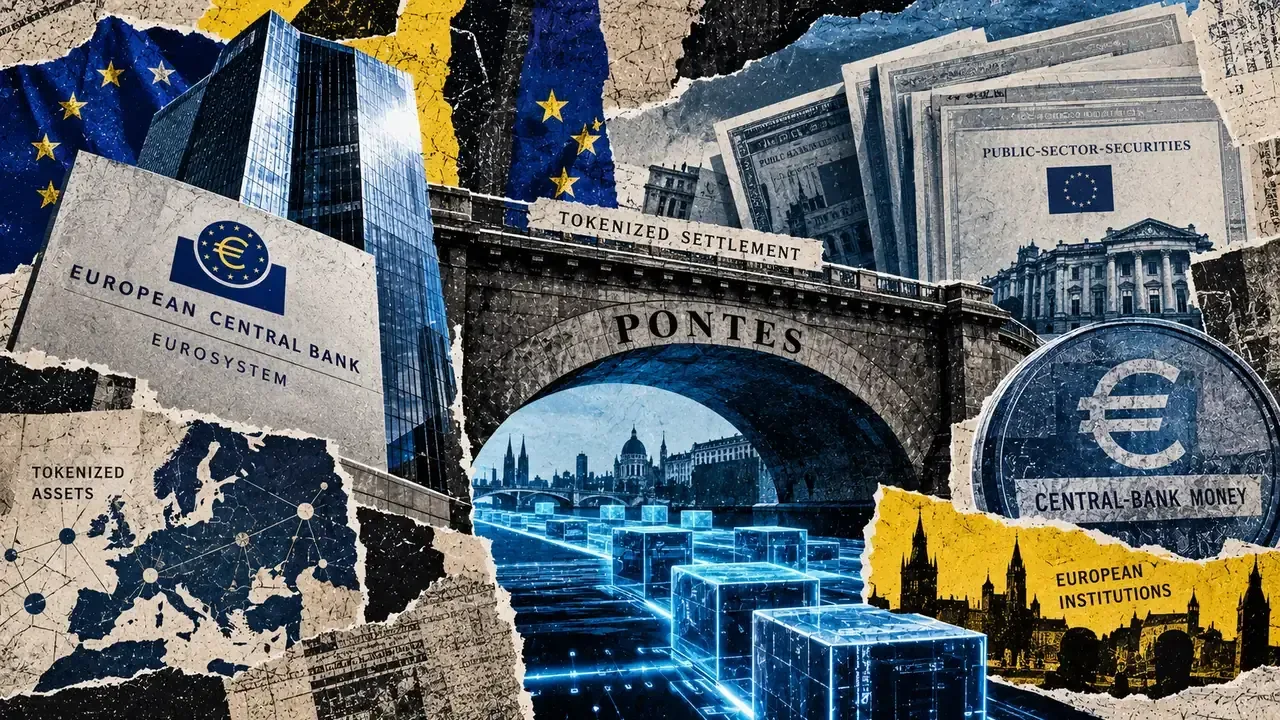
On Monday, the Eurosystem introduced Pontes, establishing an active channel for financial institutions to settle tokenized assets using central-bank money.
At the same time, the European Central Bank (ECB) started preparing to allocate a minor share of its own funds to tokenized securities, which will be settled via the Pontes network. This dual approach positions the ECB on both sides of Europe’s developing tokenized-market landscape, acting as both the infrastructure operator and an active investor utilizing the platform.
By linking distributed-ledger technology (DLT) market platforms with the Eurosystem’s established TARGET settlement services, Pontes enables the settlement of tokenized securities transactions in risk-free central-bank money. An inaugural cohort of participants—including Deutsche Bank, Santander, Société Générale, and the European Investment Bank—has already completed onboarding, alongside DLT infrastructure providers like Clearstream, Axiology, Cashlink, and SWIAT. Additional institutions are projected to integrate with the system in the near future.
André Dragosch, the Head of Research at Bitwise Europe, characterized the platform as essentially a “digital euro made available for banks,” enabling commercial lenders to settle tokenized transactions among themselves while keeping central-bank money as the foundational settlement asset.
This description highlights the potential impact of Pontes on wholesale financial markets, where the lack of access to risk-free settlement assets has historically hindered the migration of securities to distributed ledgers. Indeed, feedback from the Eurosystem’s 2024 DLT trials indicated that both public and private market participants consider access to central-bank money essential for broader industry adoption.
At launch, the platform offers a restricted suite of services, with plans to progressively introduce new features and extended operating hours ahead of full implementation in 2028. Since Monday’s rollout, the ECB has not confirmed any completed live settlements, meaning actual transaction volume will serve as the next true indicator of whether the infrastructure can build momentum beyond its initial group of onboarded participants.
ECB prepares to become a buyer on its new settlement rail
The ECB’s upcoming investment initiative expands its role beyond that of a mere infrastructure provider, giving the central bank hands-on experience with the exact transaction lifecycle it is encouraging private financial institutions to adopt.
First purchases will target euro-denominated tokenized debt issued by eurozone sovereign governments, sub-sovereign entities, agencies, and European supranational bodies. According to the ECB, utilizing Pontes for these investments will yield valuable operational insights across trade execution, settlement procedures, technology infrastructure, and portfolio management.
This tokenized allocation is expected to start small compared to the central bank’s broader portfolio. At the close of 2025, the ECB’s own-funds holdings stood at €23.1 billion, with sovereign debt representing 73% of that total. The exact size of the tokenized asset allocation and the timeline for starting purchases have not been made public; both will be decided by the ECB’s Executive Board once preparatory steps are finalized.
These own funds are administered independently of the ECB’s monetary-policy portfolios and generate revenue to help cover operational costs. By using this specific capital pool, the central bank can evaluate tokenized markets without affecting monetary policy or turning the purchases into tools for quantitative easing or interest-rate steering.
The launch of Pontes occurs long before the anticipated debut of Europe’s retail digital euro. The ECB is scheduling a 12-month consumer-facing pilot to start in the latter half of 2027, which will test the system with 36 payment service providers, merchants, and central bank personnel. A potential initial rollout of the retail digital currency is projected for 2029, pending the passage of required legislative frameworks.
Even so, the parallel initiatives demonstrate Europe’s commitment to embedding central-bank money into modern digital infrastructure through dual pathways.
Dragosch highlighted past debates regarding whether public blockchain networks might eventually support the digital euro. In 2025, the Financial Times reported that European policymakers were exploring networks like Ethereum and Solana as potential technological foundations, driven by rising anxieties over the dominance of US dollar-backed stablecoins. At the time, the ECB stated it was investigating both centralized and decentralized options and had not reached a final conclusion.
For the wholesale sector, Pontes offers an immediate pathway, bypassing the wait for a finalized retail framework. Commercial banks and asset platforms can start linking their tokenized issuance and trading systems directly to central-bank settlement. Meanwhile, the Eurosystem plans to enhance Pontes alongside the development of Appia—a broader project designed to establish a comprehensive framework for a unified European DLT financial ecosystem by 2028.
The real-world test for Pontes now hinges on transaction volumes. Onboarded institutions must determine which workflows and tokenized assets to funnel through the new system, while other banks and market participants evaluate whether to integrate in the coming months.
Furthermore, the ECB’s upcoming asset purchases will offer a key indicator of progress: the scale, timing, and specific nature of its initial investments will reveal how rapidly Europe’s new settlement network can transition from a newly launched facility into an active, everyday marketplace.
